Geometric Brownian Motion
stochastic-process · 37 views
stochastic-processstochastic
What It Is
Geometric Brownian motion --- multiplicative random walk (dS/S = μdt + σdW), the basis of Black-Scholes option pricing. Log-normal distribution with positive skew
Interpretation
Standard analysis sees: left-skewed; smooth / autocorrelated; long-range memory (persistent); volatility-clustering (bursty); low-dimensional. The atlas additionally detects Nonstationarity:adf_pvalue.
What standard analysis sees
tail heaviness0.17
asymmetry0.14
occupancy0.77
short-range corr0.96
long-range memory0.93
spectral colour0.26
periodicity0.79
complexity0.69
time-irreversibility0.33
volatility clustering0.95
multifractality0.45
dimensionality0.10
nonstationarity0.83
What the atlas adds
Nonstationarity:adf_pvalue+3.3z
unit-root nonstationarity (ADF cannot reject random-walk null)
Composition
dtypefloat64
range[-3.241, 8.882]
unique values16384 / 16384
mean ± std2.77 ± 3.22
Render Gallery
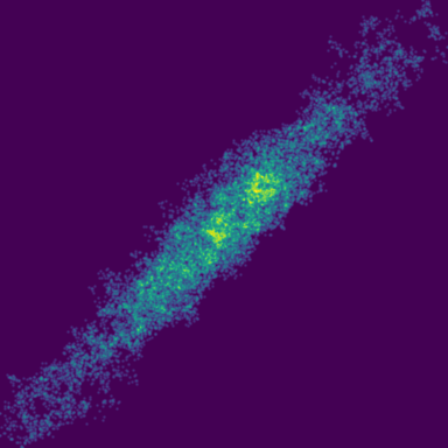
Native > phase_plotraw
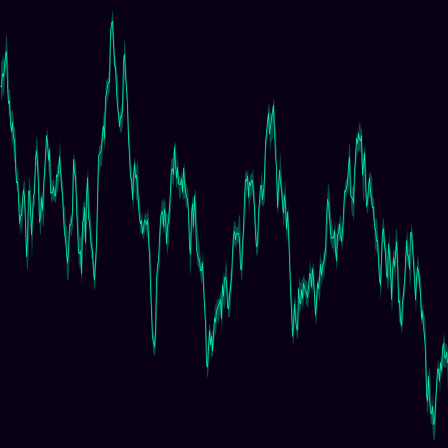
Native > timeseriesraw
Native > triple_latticeraw
Boltzmann > lag_map
Boltzmann > spin_grid
Cayley > default

Chladni > free_plate_nodal
Chladni > plate_bottom
Chladni > plate_top

Heisenberg (Nil) (centered) > signed_log_z

Heisenberg (Nil) (centered) > xy_path
Hodge–Laplacian > default

Inflation (Substitution) > barcode

Inflation (Substitution) > d_curve
Information Theory > default
Julia Set > escape_histogram
Klein Bottle > default
Laplacian > default
Logarithmic Spiral > default

Möbius-S³ > mobius_cylinder

Möbius-S³ > s2_base_map
Ordinal Partition > default

Penrose (Quasicrystal) > phi_spectrum
Persistent Homology > barcode
Persistent Homology > h1_diagram
Predictability > default
Recurrence Quantification > default
Spectral Analysis > default
Spectral Graph > default
Spirograph > mode_spectrum
Spirograph > phasor_trajectory
Symplectic > flux_grid
Symplectic > phase_space

Ulam Spiral (Sacks) > default

Ulam Spiral (Square) > default
Visibility Graph > default
Wavelet Cascade > default
Atlas Position
| Nearest neighbor | Distance | |
|---|---|---|
| Brownian Walk | 2.29 | |
| Perlin Noise | 2.73 | |
| fBm (Persistent) | 2.98 |
Which Geometries Light Up
Catch24 › Catch24:CO_FirstMin_ac | rank 5/306 | 6096.6000 |
Catch24 › Catch24:SB_BinaryStats_mean_longstretch1 | rank 5/306 | 5348.1000 |
Dodecagonal (Stampfli) › Dodecagonal (Stampfli):pisot_triplet_coherence | rank 4/306 | 0.5245 |
← / → within domain · ⇧← / ⇧→ alphabetical · ⇧← / ⇧→ inside an open render = same view across sources